

Q3 2026 QiM Fact(or) Sheet
- Market: US equities finished higher, but gains were increasingly narrow, with strong AI-linked earnings supporting cloud platforms, while higher oil prices and rising yields weighed on the broader market.
- Macro: US growth remained strong as hiring, spending and business activity all strengthened, while inflation remained sticky despite some easing in core measures. Higher energy prices and firm activity kept rate hike expectations elevated.
- Earnings: 86% of S&P500 companies beat EPS expectations, with CY2026 earnings growth estimates rising to 32.2% (earnings estimates continued to rise through the quarter despite the tougher rates and energy backdrop.)
- Countries: Japan led on the back of strong earnings and domestic reflation helping financials and many other traditionally cheap stocks. Taiwan outperformed, led by TSMC. China benefited from renewed buying in AI and internet stocks, while Korea lagged as the crowded memory chip trade corrected. France was pressured by fiscal concerns driving higher sovereign yields.
- Sectors: Energy benefited from renewed tensions in the Middle East, which pushed oil prices and boosted refiners. Health Care was supported by UnitedHealth’s beat and guidance upgrade, while Utilities lagged as the US Treasuries moved sharply higher, outweighing stronger AI data center power demand.
- Factors: Semiconductor concentration was the key differentiator. Momentum was hurt where prior AI and memory winners were most crowded, particularly in the US and Korea, while Quality benefited from sentiment rebound on continued earnings strength in profitable technology and Health Care.
- Non-US (EAFE) Value was supported by Financials and Japan.
- Low Volatility was more resilient in EM through lower exposure to hyper concentrated Korean memory producers, but struggled in the US where defensive sector tilts missed Energy and were exposed to weak Utilities.
Factor families
Exhibit 1: Q3 2026 QiM Investable factor proxies versus respective capitalization weighted indexes
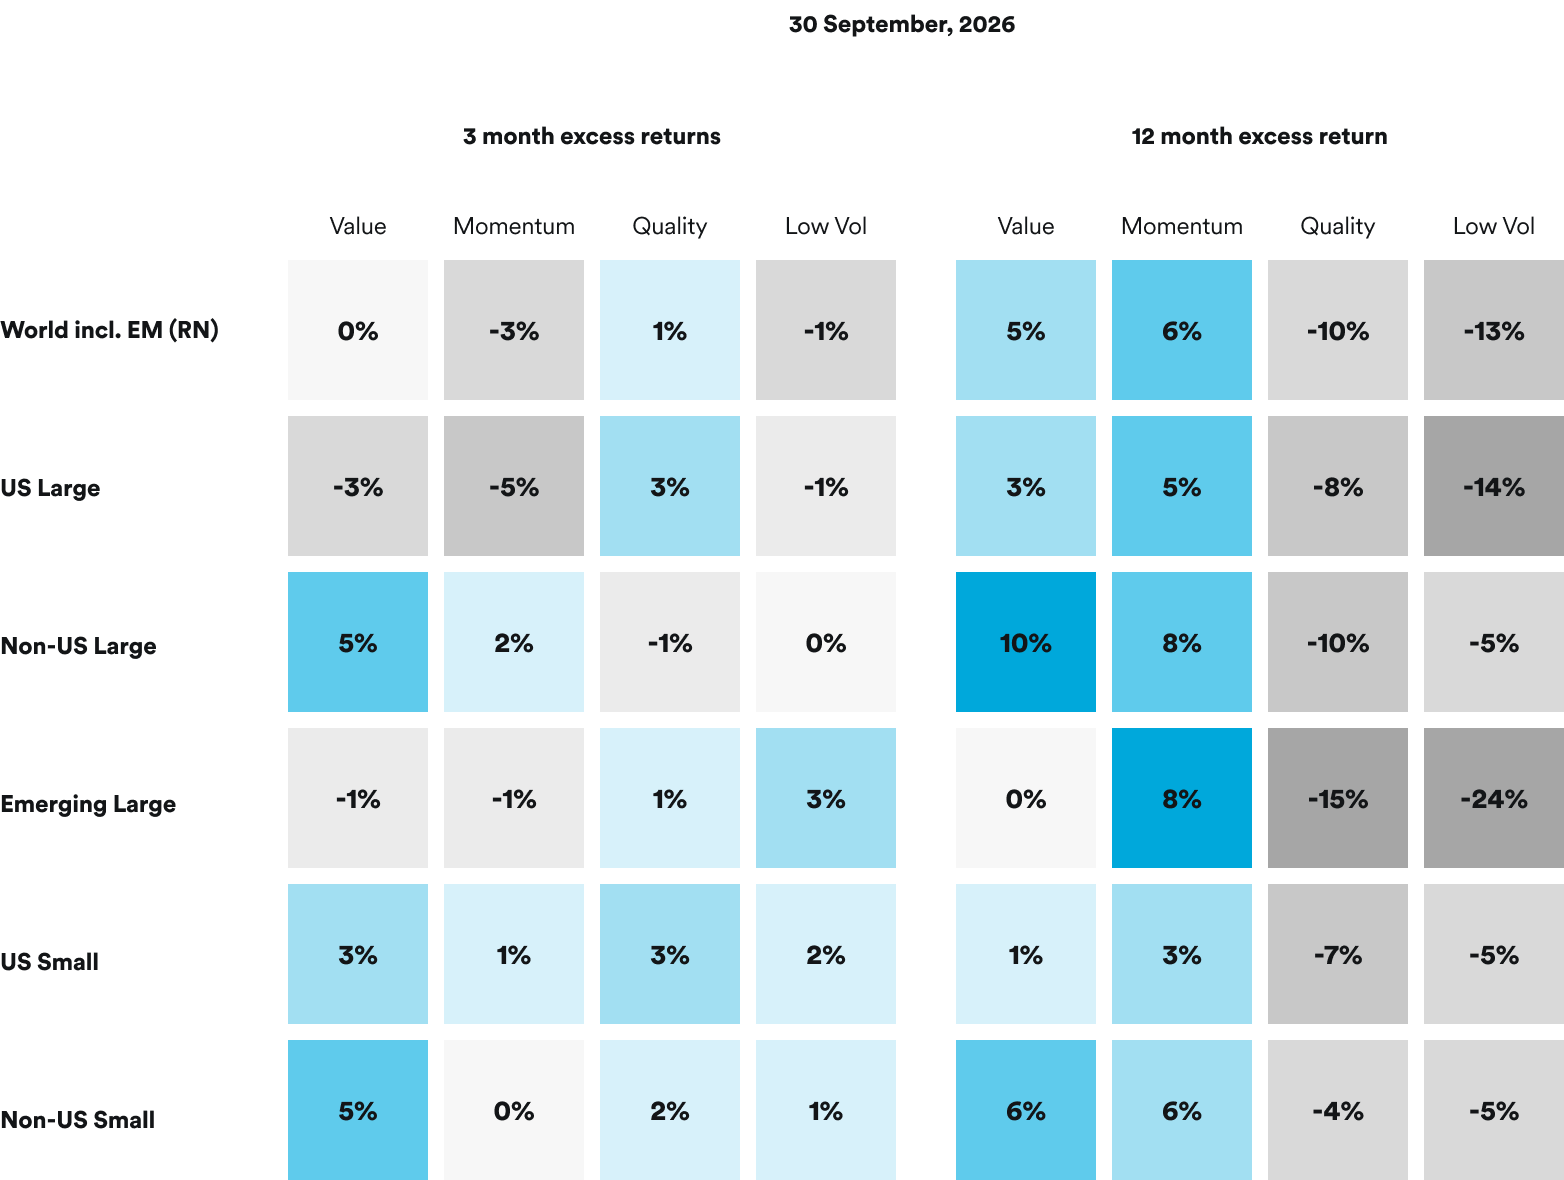
Source: SEI, based on data from MSCI, Axioma and FactSet. Data as of September 30, 2026. Returns quoted in USD. Metrics are composites of underlying ratios that SEI has determined to be appropriate measures of each factor. Data refers to past performance of top-tercile factor-proxy portfolios vs. the capitalisation-weighted benchmark and rebalanced quarterly. Returns are for illustrative purposes only and do not represent actual fund performance. Excess returns measured against (in descending order): MSCI ACWI Large Cap, MSCI USA Large Cap, MSCI EAFE Large Cap, MSCI EM Large Cap, MSCI USA Small Cap, MSCI EAFE Small Cap Indexes. Index performance returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index. Past performance is no guarantee of future results.
Adaptive outlook
Summary: Tilted further toward Value this quarter, funded mainly out of Momentum with smaller declines in Quality and Low Vol. The move was driven mainly by the interest-rate signal, which swung in Value's favor.
- Trend signals: Value's outperformance trend eased a little over the quarter while Quality and Low Vol built modestly. Overall, trend readings were fairly stable quarter over quarter.
- Valuation signals: Momentum looked meaningfully cheaper by quarter-end and picked up allocation at Quality's expense, while Value's valuation support held steady.
- Macro: The interest-rate read swung firmly in Value's favor this quarter, pushing Momentum's weight within that signal down to essentially nothing.
Exhibit 2: Q3 2026 Adaptive factor family positioning
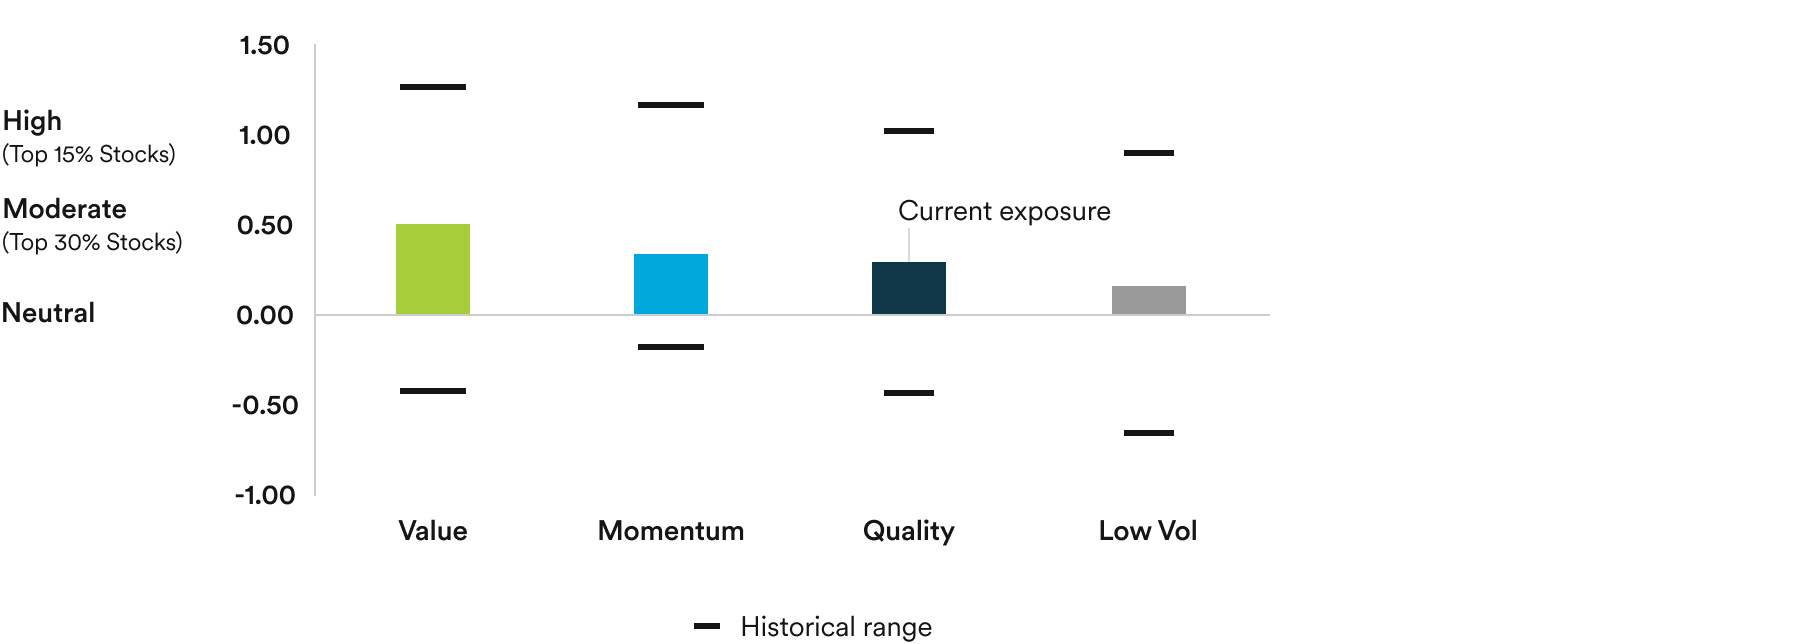
Source: SEI, the axis displays z-score exposure versus benchmark, as of September 30, 2026. Long term average exposure from January 31, 2003, to current. Benchmark: MSCI World Index.
Z-scores tell us how exposed a portfolio is to a factor, compared to a benchmark, based on what's normal for that factor. It is a common "currency" of portfolio exposures, making unrelated raw metrics like P/E or ROE comparable to each other.
A value of zero means the portfolio is neutral to the benchmark for that factor.
Higher values mean the portfolio has more exposure to that factor than the benchmark.
Economic indicators
US –Growth remains strong, as higher inflation persists
Jobs – Hiring rebounds as unemployment and claims remain low
- Nonfarm Payrolls: at 162K, above expectations and prior quarter (63K).
- Unemployment Rate: 4.1%, in line with expectations and below prior quarter (4.3%).
- Initial Jobless Claims: 204.7K quarterly average, below prior quarter average of 212.7K.
Inflation – Underlying inflation eases but remains elevated
- Core CPI: 2.4 (YoY), in line with expectations and below prior quarter (2.85%).
- Core PCE Deflator: 3.0% (YoY), below expectations and prior quarter. (3.16%).
- Hourly Earnings (preliminary): 3.1% (YoY), above expectations and below prior quarter (3.34%).
Consumer – Spending rebounds while confidence weakens
- Retail Sales: 1.2% (MoM, SA), above expectations and prior quarter (0.93%).
- Michigan Sentiment (preliminary): 47.8, below expectations and prior quarter (49.5).
- Consumer Confidence: 81.9, below expectations and prior quarter. (92.2)
Manufacturing and Services – Business activity accelerates
- S&P PMI Manufacturing, SA (preliminary): 57.0, above expectations and prior quarter (53.93).
- S&P PMI Services, SA (preliminary): 58.7, above expectations and prior quarter (51.17).
- Empire State Index, SA: 7.6, below expectations and above prior quarter (5.7).
Source: FactSet. Past performance is not a reliable indicator of future results.
The rest of the world
China - Export growth remains strong while domestic demand stays weak
- Exports: 25% (YoY), above expectations and prior quarter (19.4%).
- S&P PMI manufacturing: 52.1, above expectations and prior quarter. (51.7)
- S&P PMI services: 51.6, marginally above expectations and below prior quarter. (54.1)
- CPI: 0.8% (YoY), below expectations and prior quarter (1.2%).
Japan - Inflation rises as business activity remains resilient
- CPI Core National: 1.7% (YoY), above prior quarter (1.4%).
- S&P Manufacturing PMI (preliminary): 54.1, marginally below prior quarter (54.84).
- S&P Services PMI: 51.6, below prior quarter (52.1).
Germany - Activity strengthens as inflation rises
- CPI: 2.9% (YoY), above prior quarter (2.63%).
- S&P Manufacturing PMI (preliminary): 53.8, marginally below expectations and above prior quarter (50.28).
- S&P Services PMI (preliminary): 52.9, above expectations and prior quarter (48.59).
UK - Inflation remains elevated as services recover
- CPI Core: 2.6% (YoY), in line with expectations and prior quarter (2.59%).
- Services inflation remained at 3.4%, while goods inflation increased from 2.2% to 2.7%, keeping underlying price pressures elevated.
- S&P Manufacturing PMI (preliminary): 52.0, marginally above expectations and below prior quarter (52.54).
- S&P Services PMI (preliminary): 51.7, marginally below expectations and above prior quarter (48.78)
Source: FactSet. Past performance is not a reliable indicator of future results.
Sector and country returns
Exhibit 3: MSCI All Country World Index
Source: SEI, MSCI. As of September 30, 2026. Past performance is not a reliable indicator of future results.
Glossary and index definitions
Important information
This webpage is provided by SEI Investments (Europe) Ltd ("SIEL"). SIEL is authorised and regulated by the Financial Conduct Authority. Financial Services Register Firm Reference Number (FRN) 191713. Registered office; 1st Floor, Alphabeta, 14-18 Finsbury Square, London EC2A 1BR. Registered in England and Wales – company number 03765319. This webpage is only for the intended recipient and should not be distributed further. While considerable care has been taken to ensure the information contained within this webpage is accurate and up-to date and complies with relevant legislation and regulations, no warranty is given and no representation is made as to the accuracy or completeness of any information and no liability is accepted for any errors or omissions in such information or any action taken on the basis of this information. The views and opinions in this webpage are of SEI only and are subject to change. They should not be construed as investment advice.
This material represents an assessment of the market environment at a specific point in time and is not intended to be a forecast of future events or a guarantee of future results. Positioning and holdings are subject to change. All information as of the date indicated. There are risks involved with investing, including possible loss of principal. This information should not be relied upon by the reader as research or investment advice, (unless you have otherwise separately entered into a written agreement with SEI for the provision of investment advice) nor should it be construed as a recommendation to purchase or sell a security. The reader should consult with their financial professional for more information.
Statements that are not factual in nature, including opinions, projections and estimates, assume certain economic conditions and industry developments and constitute only current opinions that are subject to change without notice. Nothing herein is intended to be a forecast of future events, or a guarantee of future results.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties, which in certain cases have not been updated through the date hereof. While such sources are believed to be reliable, neither SEI nor its affiliates assumes any responsibility for the accuracy or completeness of such information and such information has not been independently verified by SEI.
The value of an investment and any income from it can go down as well as up. Investors may get back less than the original amount invested. Returns may increase or decrease as a result of currency fluctuations. Past performance is not a reliable indicator of future results. Investment may not be suitable for everyone.
This material is not directed to any persons where (by reason of that person's nationality, residence or otherwise) the publication or availability of this material is prohibited. Persons in respect of whom such prohibitions apply must not rely on this information in any respect whatsoever.
The information contained herein is for general and educational information purposes only and is not intended to constitute legal, tax, accounting, securities, research or investment advice regarding the strategies or any security in particular, nor an opinion regarding the appropriateness of any investment. This information should not be construed as a recommendation to purchase or sell a security, derivative or futures contract. You should not act or rely on the information contained herein without obtaining specific legal, tax, accounting and investment advice from an investment professional.
The views contained herein are not to be taken as advice or a recommendation to buy or sell any investment in any jurisdiction. Our outlook contains forward-looking statements that are judgments based upon our current assumptions, beliefs and expectations. If any of the factors underlying our current assumptions, beliefs or expectations change, our statements as to potential future events or outcomes may be incorrect. We undertake no obligation to update our forward-looking statements.
In the UK and the EEA this information issued in the UK by SEI Investments (Europe) Ltd, 1st Floor, Alphabeta, 14-18 Finsbury Square, London EC2A 1BR which is authorised and regulated by the Financial Conduct Authority. Investments in SEI Funds are generally medium- to long-term investments.
This information is made available in the Middle East and Australia FOR PROFESSIONAL (non-retail) USE ONLY by SIEL.
Any questions you may have in relation to its contents should solely be directed to your Distributor. If you do not know who your Distributor is, then you cannot rely on any part of this document in any respect whatsoever.
Issued in South Africa by SEI Investments (South Africa) (Pty) Limited FSP No. 13186 which is a financial services provider authorised and regulated by the Financial Sector Conduct Authority (FSCA). Registered office: 3 Melrose Boulevard, 1st Floor, Melrose Arch 2196, Johannesburg, South Africa.
QiM is a specialist quantitative investment management team within SEI’s Investment Management Corporation (SIMC). The team is responsible for the research, development, and management of quantitative investment portfolios. QiM employs a disciplined, active investment process that targets companies demonstrating robust fundamentals and positive performance trends, with a particular emphasis on value, quality, and momentum factors. The team operates from offices in London, UK, and Oaks, PA, USA
This content is restricted. Please confirm you are a qualified professional investor.